
For more information speak to one of our brokers
Find your local broker
When interest rates are historically low, considering a remortgage makes sense. Borrowers should not become complacent over declining mortgage rates, as the current lending environment is unlikely to continue indefinitely. (Source: *Moneyfacts, March 2019 release)
With around 5,000 mortgage products out there, meeting a wide range of needs, it can also be a confusing process that highlights the need for advice. So, it’s no wonder that 85% of all mortgages continue to go through intermediaries (such as us). (Source: *iress, 2018 Mortgage Efficiency Survey, October 2018)
These days there are far stricter rules applied to ‘evidencing of income’ and ‘affordability’. They are in place to ensure that borrowers are stress-tested to see if they can, not only meet the current payments but are also able to cope should the interest rate rise. These rules apply both to a new mortgage and a remortgage.
In this respect, different lenders may interpret the rules in different ways, meaning that if you can’t get the loan you need from one, you may from another. This is a further reason for securing advice from an adviser who is operating in this marketplace, day-in, day-out. Our involvement may also help to protect your credit score, by not applying to too many different lenders.

We also recognise that most of you will have time-pressed lives. In which case, we’d endeavour to help reduce the hassle of filling out forms and applications.
Furthermore, we would hold your hand throughout the remortgage process, and try to liaise with the various parties along the way.
Of course, you can undertake this whole remortgage process yourself. For example, if your deal period is coming to an end, then you may consider remortgaging with the same lender because you feel they delivered the most suitable deal for you last time.
However, in this dynamic mortgage environment, lenders might be chasing market share at different times, so it may not be the best option to limit yourself to what’s on offer from just one of them.
That’s why it makes sense to ask us to assess the wider marketplace. It is an important process, even if the upshot is that you stay where you are.
In the first instance, to get a feel for payments against the interest rate you’re currently on versus what you believe could be on offer; do check out the mortgage calculator below to see how this may pan out.
Here’s how to use the mortgage payments calculator: A £100,000 mortgage over 25 years, charged at a 2% interest rate would cost 100 x £4.24 (for Repayment) = £424 per month.
Monthly payments for a mortgage per £1,000 borrowed over 25 years.
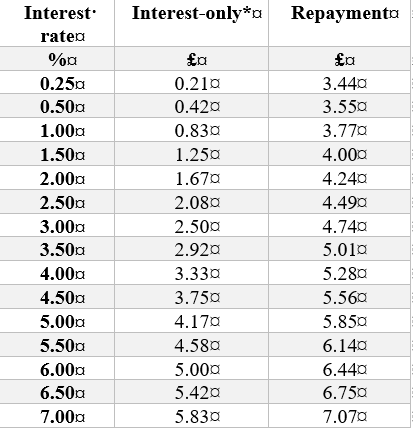
* Excludes any payments to a separate savings scheme, to help pay off the capital amount borrowed.
This calculator only provides a guide to monthly payments and does not guarantee eligibility for a mortgage. The actual amounts that you may have to pay may be more or less than the figures shown. Please contact us for a personalised illustration.
If you would like to receive our Newsletter then please complete the form below. Before doing so you can read our Privacy Policy here.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE. A typical fee is £295. Ask for a personalised illustration. The Mortgage Bureau is a trading name of A.M. Mortgages (UK) Ltd. Authorised and regulated by the Financial Conduct Authority. The Financial Conduct Authority does not regulate some aspects of Buy to Let mortgages.